Utah Down Payment Assistance: Salt Lake County Buyer Options
Utah down payment assistance programs can help eligible Salt Lake County buyers cover part of their upfront cash requirement, but the type of help, eligibility rules, and repayment terms vary widely by program and lender. This guide explains the main categories of assistance available to Utah buyers, how to verify current program details, and how assistance differs from a buyer credit offered through your broker.
Quick Answer
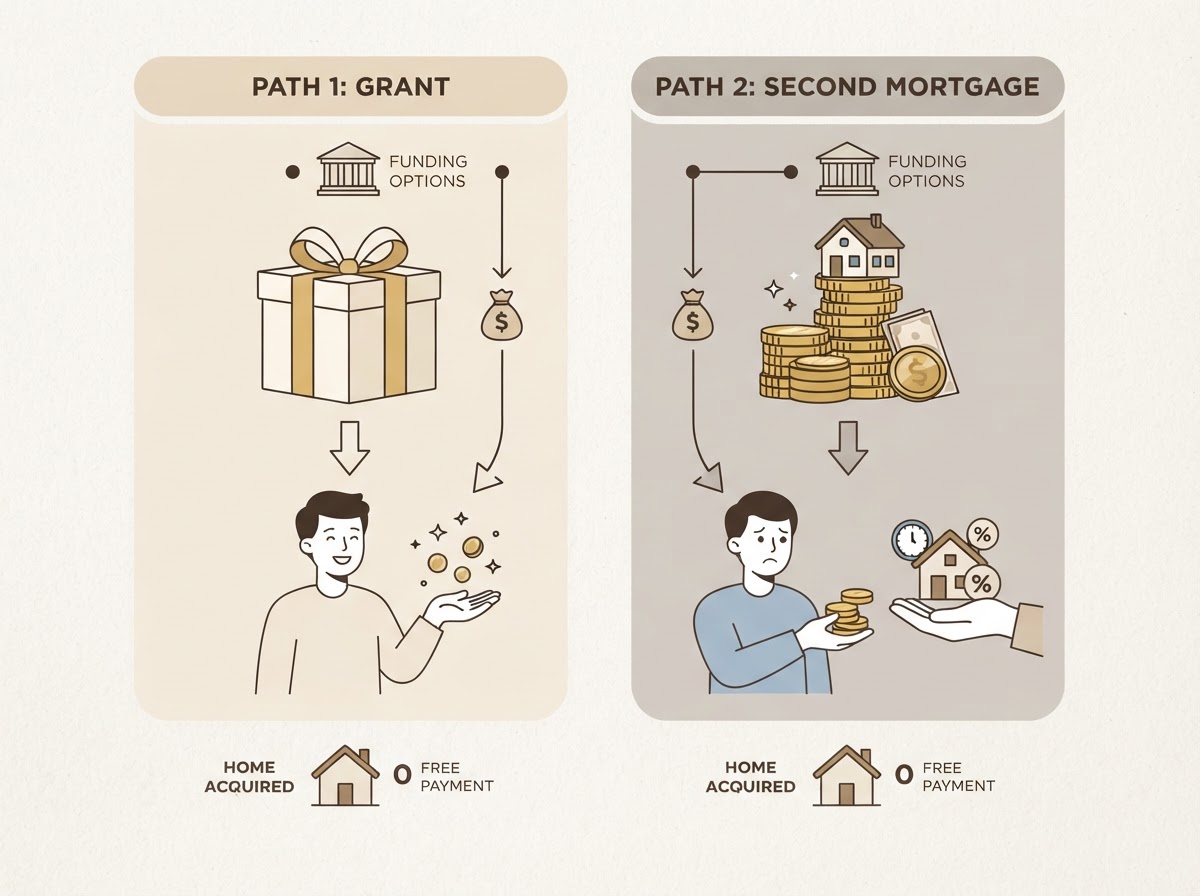
Utah down payment assistance generally comes as either a grant (no repayment) or a silent second mortgage (repaid on sale, refinance, or after a set term). The Utah Housing Corporation (UHC) offers the most widely used statewide programs, and some cities and nonprofits run local options. Eligibility depends on income, purchase price, loan type, and first-time-buyer status — and program funding and terms change, so verify everything with a participating lender before relying on it.
Key Takeaways
- Two main structures: Assistance is usually a grant or a forgivable/deferred second mortgage — know which one before you budget.
- UHC is the primary source: The Utah Housing Corporation runs the main statewide down payment assistance programs.
- Eligibility is specific: Income limits, purchase-price caps, and first-time-buyer requirements vary by program and change annually.
- Assistance ≠ broker credit: Down payment assistance is a lender/program benefit; Scott Allen's up-to-$3,000 buyer credit is a separate, broker-side credit toward eligible closing costs.
- Verify before you commit: Program funding can run out or change; confirm availability with a participating lender.
- Stacking may be limited: Some programs restrict combining assistance with seller concessions or other credits — ask your lender.
Types of Down Payment Assistance in Utah
Down payment assistance (DPA) is not one uniform product. Understanding the structure helps you compare offers and avoid surprises later.
| Type | How it works | Repayment |
|---|---|---|
| Grant | A gift of funds applied to your down payment or closing costs. | No repayment required (subject to program terms). |
| Forgivable second mortgage | A second lien that is forgiven over a set occupancy period (e.g., 5–10 years). | Forgiven if you live in the home for the required period; prorated repayment if you sell early. |
| Deferred second mortgage | A second lien with no monthly payments; repayment deferred. | Repaid when you sell, refinance, or pay off the first mortgage. |
| Low-interest second mortgage | A second loan with monthly payments at a below-market rate. | Monthly payments alongside your first mortgage. |
Program availability and structure change. Confirm current options with a participating lender.
Utah Housing Corporation Programs
The Utah Housing Corporation (UHC) is the primary statewide source of down payment and closing-cost assistance for Utah buyers. UHC partners with approved lenders to offer first mortgages paired with assistance options. Common program families include:
- FirstHome Loan: A 30-year fixed-rate loan for first-time buyers (or buyers in targeted areas), often paired with down payment assistance.
- HomeAgain Loan: For buyers who may not meet FirstHome eligibility, with different income or purchase-price parameters.
- Score Loan: For buyers with lower credit scores who still qualify, with specific credit minimums.
Each UHC program has its own income limits, purchase-price limits, and assistance structure. Verify current terms — including whether assistance is a grant or second mortgage — on the Utah Housing Corporation website or with a UHC-approved lender.
Eligibility and Income Limits
Eligibility for down payment assistance is not automatic. Common requirements include:
- Income limits: Most programs cap household income, often by county and household size.
- Purchase-price limits: Programs set maximum home prices, which vary by area.
- First-time buyer status: Some programs require you to be a first-time buyer (typically no ownership in the past 3 years); others are available in targeted areas regardless.
- Occupancy: Assistance is for primary residences, not investment properties.
- Approved loan type: Assistance is typically paired with FHA, VA, USDA, or conventional loans through approved lenders.
Income and purchase-price limits are updated periodically. Do not rely on older figures — confirm the current limits with your lender.
Repayment and Resale Rules
If your assistance is a second mortgage rather than a grant, understand when it must be repaid:
- Sale of the home: The second mortgage is typically due when you sell.
- Refinance: Paying off or refinancing the first mortgage may trigger repayment of the second.
- Occupancy period: Forgivable seconds require you to live in the home for a set number of years; selling early may require prorated repayment.
- Lease restrictions: Some programs prohibit renting the home during the assistance period.
Read the assistance agreement carefully and ask your lender to explain the exact repayment trigger before closing.
Questions to Ask Your Lender
- Which down payment assistance programs am I eligible for based on my income and the home price?
- Is the assistance a grant or a second mortgage, and what are the repayment terms?
- What are the current income and purchase-price limits for Salt Lake County?
- Can I combine this assistance with seller concessions or a broker credit?
- Are there recapture or repayment penalties if I sell or refinance early?
- How long does the program funding last, and is it currently available?
Assistance vs. Scott Allen's Buyer Credit
Down payment assistance is a lender or government program benefit. It is separate from the credit Scott Allen may offer eligible buyers. Eligible buyers may receive a credit of up to $3,000 toward eligible closing costs, prepaid expenses, or interest-rate buydowns. Terms and eligibility apply, including lender approval and transaction requirements. This credit does not replace down payment assistance — it is a separate, broker-side credit. Ask Scott and your lender whether combining the two is permitted in your transaction. See how Scott's buyer credit works and the Utah closing-costs guide for more detail.
Frequently Asked Questions
Does Utah offer free down payment assistance?
Some Utah programs provide grants that do not require repayment, while others offer second mortgages that are forgivable or deferred. Availability and structure change — verify current options with a participating lender or the Utah Housing Corporation.
Who qualifies for Utah down payment assistance?
Eligibility depends on household income, purchase price, loan type, and first-time-buyer status, with limits that vary by program and area. Check current income and price limits with your lender before assuming you qualify.
Can I use down payment assistance in Salt Lake County?
Yes. Utah Housing Corporation programs are available statewide, including Salt Lake County, subject to income and purchase-price limits for the area. Some local or nonprofit programs may also be available.
Is down payment assistance the same as Scott Allen's buyer credit?
No. Down payment assistance is a lender or program benefit. Scott's up-to-$3,000 credit is a separate broker-side credit toward eligible closing costs. Terms and eligibility apply, and combining both requires lender approval.
Do I have to repay down payment assistance?
It depends on the program. Grants require no repayment; forgivable or deferred second mortgages are repaid when you sell, refinance, or fail to meet occupancy requirements. Read your assistance agreement and confirm terms with your lender.
Can I combine assistance with seller concessions?
Sometimes. Some programs restrict stacking assistance with other credits. Ask your lender whether combining down payment assistance, seller concessions, and a broker credit is allowed in your loan type.
Questions About Down Payment Assistance?
Scott Allen helps Salt Lake County buyers understand their upfront-cash options and connect with participating lenders. Eligible buyers may receive a credit of up to $3,000 toward eligible closing costs, prepaid expenses, or interest-rate buydowns. Terms and eligibility apply, including lender approval and transaction requirements.
Understand the upfront budget before you choose the home.
Get a Salt Lake County Buyer Consultation or call (801) 424-9283.