Cost of Living Salt Lake City: A Homebuyer's Monthly Budget
Cost of living in Salt Lake City for a homeowner is more than just a mortgage payment. Property taxes, insurance, HOA fees, utilities, transportation, and maintenance all add to your monthly housing cost. Understanding the full picture before you buy helps you set a realistic budget and avoid surprises after move-in. This guide breaks down the components of a homeowner's monthly budget with a transparent illustrative example.
Quick Answer
A homeowner's monthly cost of living in Salt Lake City includes PITI (principal, interest, taxes, insurance), plus HOA fees if applicable, utilities (electricity, gas, water, internet), transportation, and maintenance. A common guideline is to budget roughly 1% of the home's value per year for maintenance. Your actual costs depend on the home, loan, and lifestyle — build a complete monthly budget, not just a mortgage estimate.
Key Takeaways
- PITI is the core: Principal, interest, property taxes, and insurance make up the base monthly housing payment.
- HOA adds to it: If the property has an HOA, dues are a recurring monthly cost.
- Utilities vary: Electricity, gas, water, sewer, trash, and internet depend on the home and usage.
- Maintenance is ongoing: Budget roughly 1% of the home's value per year for upkeep.
- Transportation counts: Commute costs — gas, transit, vehicle expenses — are part of your monthly budget.
- Build a full budget: Compare total monthly costs, not just the mortgage, when deciding what you can afford.
Components of a Homeowner's Monthly Budget
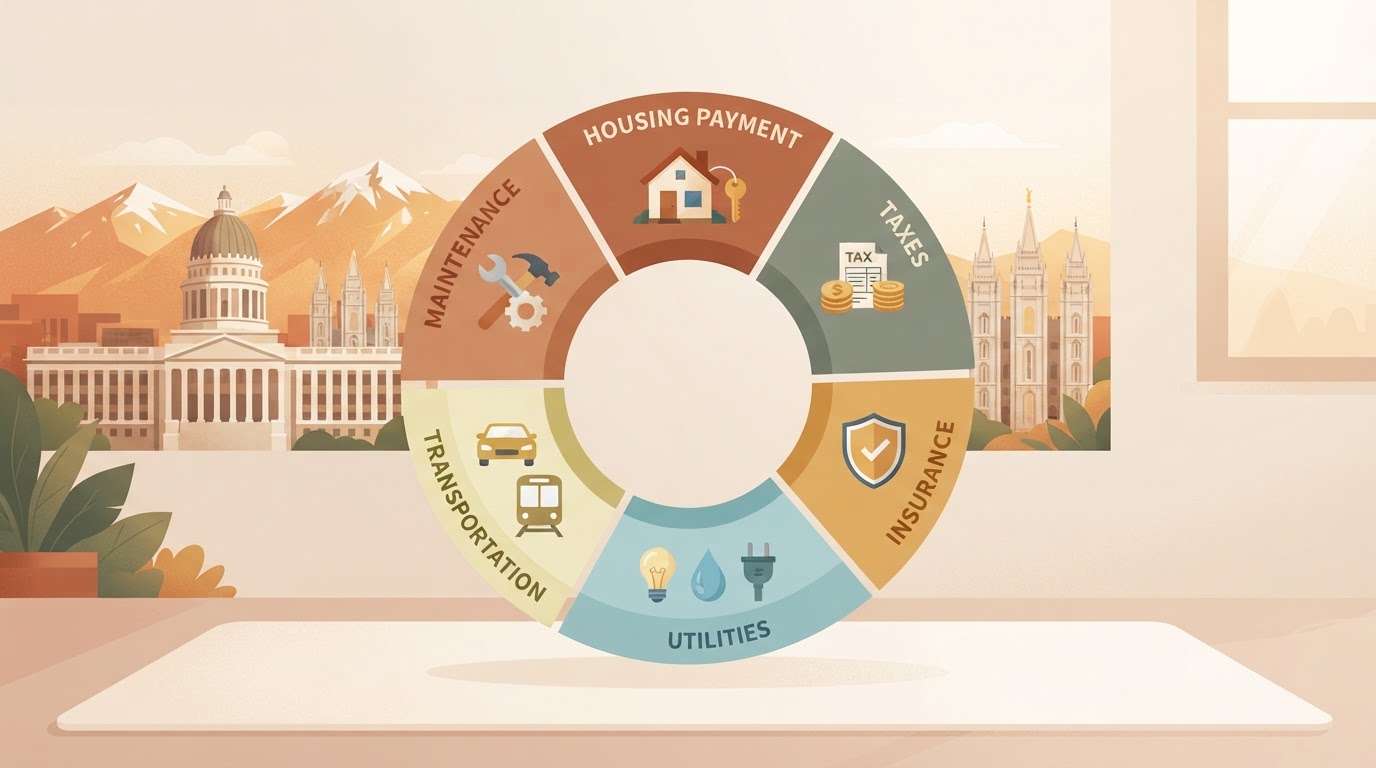
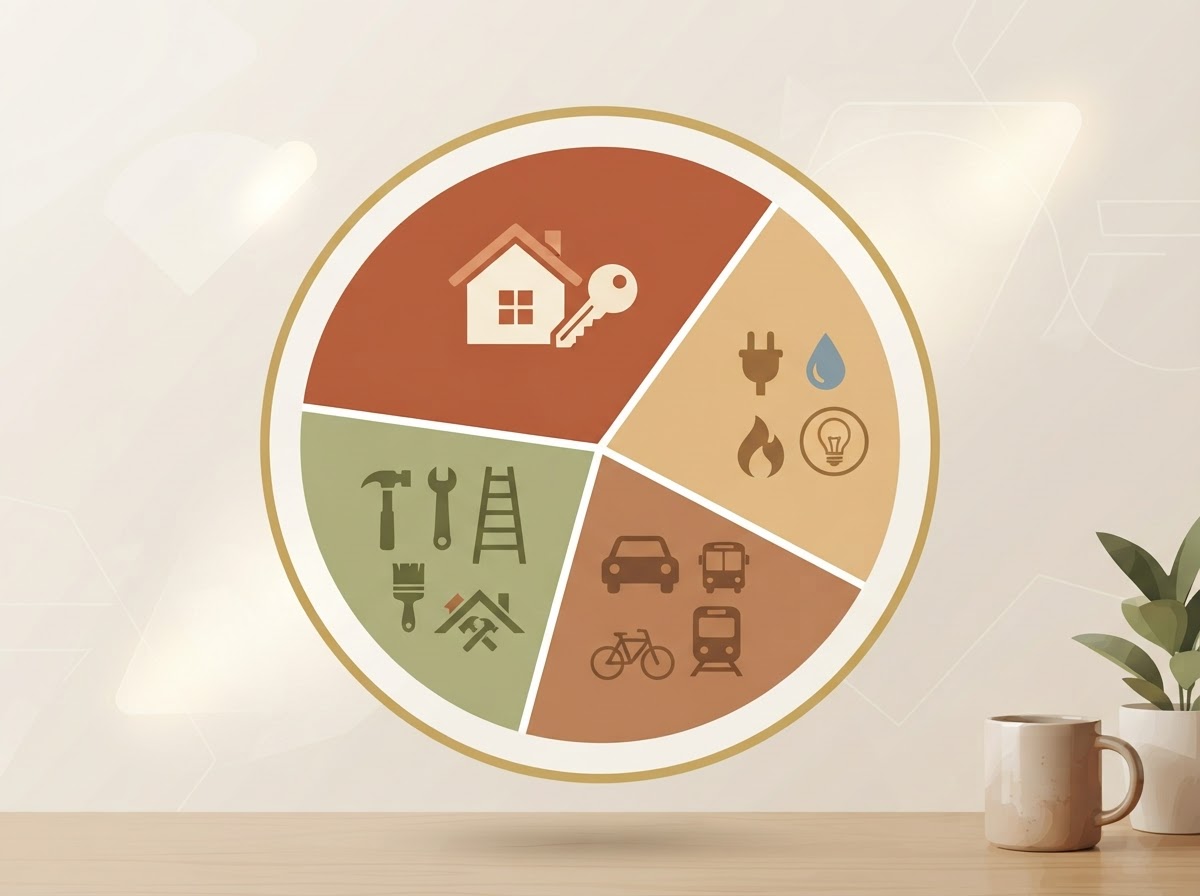
A homeowner's monthly budget includes several categories beyond the mortgage:
- Housing payment (PITI): Principal, interest, property taxes, insurance
- HOA fees: If the property is in an HOA
- Utilities: Electricity, gas, water, sewer, trash, internet
- Transportation: Gas, transit passes, vehicle costs
- Maintenance: Ongoing repairs and upkeep
Illustrative Monthly Budget
This illustrative example shows a monthly budget for a hypothetical $500,000 home with 5% down. Figures are examples for comparison — not quotes, actual costs, or guarantees.
| Category | Illustrative Monthly Cost |
|---|---|
| Principal & interest | ~$2,700 |
| Property taxes | ~$350 |
| Homeowner's insurance | ~$150 |
| Mortgage insurance (PMI) | ~$200 |
| HOA (if applicable) | ~$50–$300 |
| Utilities (electricity, gas, water, internet) | ~$300–$500 |
| Maintenance (1%/year ÷ 12) | ~$400 |
| Total (illustrative) | ~$4,150–$4,600 |
Illustrative example only — not a quote or actual cost. Your actual costs depend on the home, loan, location, and lifestyle. Verify all figures with your lender and service providers.
Housing Payment (PITI)
Your core housing payment is PITI: principal and interest on the loan, plus property taxes and homeowner's insurance. If you put down less than 20%, add private mortgage insurance (PMI). Property taxes in Salt Lake County vary by city and school district — see our property tax guide. Use your lender's Loan Estimate to see your exact PITI.
HOA Fees
If the property is in a homeowners association, HOA dues are a recurring monthly cost. HOA fees cover shared amenities and maintenance but add to your monthly budget. Review HOA documents before buying — see our HOA fees guide. Ask what the dues cover, whether increases are expected, and whether there are pending special assessments.
Utilities
Utilities include electricity (Rocky Mountain Power), natural gas (Dominion Energy), water and sewer (your city), trash (your city), and internet (multiple providers). Costs vary with the home's size, insulation, season, and your usage. When moving, set up utilities in advance — see our moving guide for provider details.
Transportation
Transportation costs include gas, vehicle maintenance, and transit. Salt Lake City has UTA TRAX and FrontRunner transit options. Your commute distance and route affect monthly transportation costs — factor this into your neighborhood choice. See our neighborhood guide for commute considerations.
Maintenance
Homeowners are responsible for maintenance and repairs. A common guideline is to budget roughly 1% of the home's value per year for upkeep — some years you spend less, some more. Set aside money monthly so you are prepared for repairs (roof, HVAC, water heater) without financial strain. Renters do not pay for maintenance — owners do.
Frequently Asked Questions
What is the cost of living in Salt Lake City for a homeowner?
A homeowner's monthly cost includes PITI (principal, interest, taxes, insurance), HOA fees if applicable, utilities, transportation, and maintenance. Build a full monthly budget — not just a mortgage estimate — to understand what you can afford.
How much are utilities in Salt Lake City?
Utilities include electricity (Rocky Mountain Power), gas (Dominion Energy), water and sewer (your city), trash (your city), and internet. Costs vary with home size, season, and usage. Contact providers for estimates at your specific address.
How much should I budget for home maintenance?
A common guideline is roughly 1% of the home's value per year for maintenance. Some years you spend less, some more. Set aside money monthly so you are prepared for repairs without financial strain.
Does the mortgage payment include taxes and insurance?
Often yes. With an escrow account, your monthly payment includes principal, interest, property taxes, and insurance (PITI). The lender pays the tax and insurance bills when due. Review your Loan Estimate for the exact breakdown.
How do HOA fees affect my monthly budget?
HOA dues are a recurring monthly cost on top of PITI. They cover shared amenities and maintenance. Review HOA documents before buying to understand what dues cover and whether increases or assessments are expected.
Can Scott Allen's buyer credit help with monthly costs?
Eligible buyers may receive a credit of up to $3,000 toward eligible closing costs, prepaid expenses, or interest-rate buydowns. Terms and eligibility apply, including lender approval and transaction requirements. The credit reduces your upfront cash to close, which can free up savings for your monthly budget. Ask Scott how it fits your purchase.
Building Your Monthly Budget?
Scott Allen helps Salt Lake County buyers understand the full cost of homeownership and budget realistically. Eligible buyers may receive a credit of up to $3,000 toward eligible closing costs, prepaid expenses, or interest-rate buydowns. Terms and eligibility apply, including lender approval and transaction requirements.
Understand the upfront budget before you choose the home.
Get a Salt Lake County Buyer Consultation or call (801) 424-9283.